Wednesday, December 1, 2010

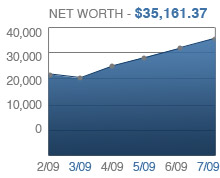
November 10 Net Worth 97K: Thankful for

November is done and whew...what a month! If you look closely you will see there is a new value in "Real Estate/Home Value" and in Mortgage. We purchased our first home this month. We did it despite my thinking that the housing market is going remain falling. We are trying to start a life and we found a home that we love. We also do not look at this an investment but more of a home where live and become a family, which is way more valuable than any price of money. We feel we got a great deal and we are not going to look back. We are happy and thats all I have to say...
Lets break it down:

Cash & Savings: We have been saving up for a house down payment but looks like we got one heck of deal on a home, so we will be keeping most of this. Our first goal is to get about 50K in the bank(cash) for saving before we really start putting our money to work. This has grown despite purchasing some major things for our new home(washer, dryer, and fridge). This bracket holds the funds for insurance, auto maintenance, Roth IRA, and vacation. It also holds my monthly budget in it. The rest is used on a daily bases for covering expenses, mortgage, food, auto, etc...

Stocks/Brokerage: Has been remained a good run with my brokerage account the last couple of months. I have purchased a few other stocks Silver Wheaton(SLW), Fronteer Gold (FRG) and Silvercorp Metals, Inc. (SVM). I sold off my GLD with a 20% gain from where I purchased and hoping these remaining gaining like they have the last couple months. I am just saving up some cash in the mean time to start dollar cost averaging into these. I am up around 13% in these. The list of stocks I currently own: (SLW)(FRG)(SVM)(EXC)(PWE)(PHYS)(EGO)(AUY)(AVARF)(RGLD)(ZQK)(XOM)(CVX).

*As you can see I am heavy in commodities in my brokerage account. This is all based on my thought that over the next decade the best investments are going to actually be in hard assets. My Roth/IRA/401k are in pretty common index funds and mutual funds so I figure I can go more risky with brokerage. I believe these will out perform equities in the next decade and if nothing else I feel more comfortable with my portfolio being diverse. I am bearish on the US Dollar and US Economy, I believe that trillion dollar deficits are not going bode well for the USA.

Retirement 401k: This bracket is just both my wife and my retirement, adding money to our retirement funds every month. Steady growth here...(update - the fed announced quantitative easing or money printing and the market has kinda been up and down, will wait and see what happens here.

Retirement IRA's: Still having some cash on the sideline and will figure out what this market wants to do and see if I can put it to work. In this bracket I have all Vanguard Funds (VTSMX, VGSTX, VEIEX, VGPMX)

Real Estate: So this is a new category, based off getting 100% financing, right now its not even an asset based of not having any equity in our home. The plan here is to keep our money that we were going to put down as a down payment in the bank or investments. We will try and hedge our payments with trying to pay off the home in 10-15 yrs depending on what comes our way. This might change along the way depending on kids, economy, jobs and so forth.

Debts and Liabilities -

Credit Cards: Debt for home stuff, will be paid off without any interest.

Car Loan: I am paying 4% APR on it so I am paying a little, but not a ton. Still looking to pay it off early-will probably be a goal this or next year. Now that we don't need to save up on the downpayment we might have to start paying a bit more per month even though our mortgage will be higher than we are paying now...will keep you posted.

Home Mortgage: Sending off first payment today, more to come in the next few years :)

I am so looking forward to hitting 100k in net worth hopefully in the next month or two, we have come so far in just two short years. I am blessed to have what I do and during these hard time for most families, we have been able to create a small amount of wealth.

In this time of year we will be thankful for what we have and hopefully spread some cheer over the holidays! We will be supporting a child at an elementary school, along with a family that is in need. My family decided not to give gifts this year but to sponsor a family who's mother is dying. We will try and donate to more as they arise.

Tuesday, November 2, 2010

Is Gold a dead asset?

The following if from one of my favorite websites FOFOA:

'The falling price of Gold has had various effects on people. The common person says, "Of course it is falling, because Gold has been demonetized." The Goldheart knows better, so the falling price has a more remarkable effect, bringing out insecurities and irrationalities of some. Though these people don't question that Gold is money, their insecurities start to question whether the world really needs money at all... that somehow this greatest device of mankind has been antiquated. Simply preposterous. If they knew the truth they would confidently buy today at triple the price and call it a bargain of a lifetime. People ask, "Why waste effort to dig up Gold from the ground, only to rebury it in vaults?" I say, "For the same reason the central banks toil to print millions of fancy notes that nobody reads. If you've read one, you've read them all." The effort is needed to prevent cheating, though we easily see the fancy cash does not stem the abusive tide of money from nothing. People also say, "Gold is a dead asset. It does not earn interest." What is the point of such a comment, to demonstrate their naiveté? Did banks not pay interest when coins were stamped from Gold?

You see, it is not the nature of money itself to earn interest, but rather, it is the investment risk that maybe earns a reward. A modern dollar in a shoebox is as a Gold coin beside it. No interest for either. You should know the interest paid by a bank savings account is not a product of the money itself, but instead it is the rewards on the risk the bank takes with the money you have provided for their investment use. Sometimes these banks choose poorly, and in those cases even the modern dollar earns no interest, and does not come back at all--lost with the closing of the bank doors. Money must be risked (invested) to expect a yield, and in this regard, the big players in the world risk Gold money as they do paper money (though often not as aggressively), while the small players are content with the shoebox yield. You are forced to be more aggressive (more risky) with paper because its value dies quickly, unlike Gold that stands forever even in a shoebox of no risk.'

Thursday, October 21, 2010

How I See the World Today | Jim Rogers

Jim Rogers is one of my favorite investors to listen to. These are a must watch:


Friday, October 1, 2010

September 2010 Net Worth: 90K, I can smell 100K!

August and September are all in the books and things keep looking up despite whats going on. Thats because the wife and myself have combined all of our money. We still have some tinkering to do with her retirement and such but overall we are feeling good. That is another reason I did not put up our net worth last month so bear with me.
Lets break it down:

Cash & Savings: Huge jump since last time I posted our net worth, this is mainly due to combining my wife's saving and my savings. We have been saving up for a house down payment but looks like we got one heck of deal on a home, so we will be keeping most of this. Our first goal is to get about 50K in the bank(cash) for saving before we really start putting our money to work. We have to purchase some major things for our new home(washer, dryer, and fridge) so this will be drained a bit over the next couple months. This bracket holds the funds for insurance, auto maintenance, Roth IRA, and vacation. This is why it can be a little deceiving, it also holds my monthly budget in it. It has about 13-15k sitting around as savings the rest are funds that are going to be used at some point over the year. The rest is used on a daily bases for covering expenses, rent, food, auto, etc...

Stocks/Brokerage: Has been a good run with my brokerage account the last couple of months. I decide to go ahead and pull the trigger on Exelon Corp. I am just saving up some cash in the mean time to start dollar cost averaging into these. Overall I am up around 10% in these. The list of stocks I own (EXC)(PWE)(PHYS)(GLD)(EGO)(AUY)(AVARF)(RGLD)(ZQK)(XOM)(CVX).

*As you can see I am heavy in commodities in my brokerage account. This is all based on my thought that over the next decade the best investments are going to actually be in hard assets. My Roth/IRA/401k are in pretty common index funds and mutual funds so I figure I can go more risky with brokerage. I believe these will out perform equities in the next decade and if nothing else I feel more comfortable with my portfolio diverse. I am bearish on the US Dollar and US Economy, I believe that trillion dollar deficits are not going bode well for the USA.

Retirement 401k: This bracket is just both my wife and my retirement, adding money to our retirement funds every month. Big tick up this month because of combining...we will wait and see how the stock market plays out come the fall. (update - Fall is here and based off quantitative easing or money printing coming down the line, I am starting to think the market might raise dramatically, as money will have to flow somewhere)

Retirement IRA's: So I have jumped back into some funds as I had a large amount of cash sitting on the sidelines. I put most into precious metals & mining fund(VGPMX). In this bracket I have all Vanguard Funds (VTSMX, VGSTX, VEIEX, VGPMX)

Debts and Liabilities - Vehicle under 7K!! Credit Cards done...

Credit Cards: don't have much to say here! $0.00

Car Loan: I am paying 4% APR on it so I am paying a little, but not a ton. Still looking to pay it off early-will probably be a goal this or next year. Now that we don't need to save up on the downpayment we might have to start paying a bit more per month even though our mortgage will be higher than we are paying now...will keep you posted.

I am still extremely bearish on the world economy and the US economy...We are headed for a financial storm and it is very important for all of us to be up to date on current events. It time to be prepared for the worse and pray for the best.

Thing will be getting shifted here and there over the next few months with everything we have gong on with the home purchase and combining finances but overall I feel pretty good and cannot wait to see what happens come of end of year to see how far we have come. Until then good luck with your own budget and growing your wealth.

Thursday, September 9, 2010

Is Ayn Rand’s Atlas Shrugged Future Possible?

I highly suggest you read Dollar Commentary's post "Is Ayn Rand’s Future Possible?" DC has done an great job of summing up Atlas Shrugged and where we as a country could be heading.

Read More at www.dollarcommentary.com

I have been saying, if you have ever wanted to read Atlas Shrugged,now is the time because as you read the book, you turn on the TV and the ideas and situations that Rand talks about in the book are happening everyday.

Thursday, September 2, 2010

The Sacred Cow

Socialism: If you have two cows, you give one to your neighbor.

Communism: If you have two cows, you give them to the government and the government then gives you some milk.

Fascism: If you have two cows, you keep the cows and give the milk to the government; then the government sells you some milk.

New Dealism: if you have two cows, you shoot one and milk the other; then you pour the milk down the drain.

Nazism: If you have two cows, the government shoots you and keeps the cows.

Nanny Stateism: If you have two cows, we’re going to show up at your house at dawn with a cease-and-desist letter and forbid you to do anything useful with their milk until you comply with General Laws Chapter 94, Sections 13 and 16 through 16K, Chapter 94A, and the regulations found in 330 CMR 27.00 et seq.

Capitalism: If you have two cows, you sell one and buy a bull.

Monday, August 30, 2010

Jim Sinclair's Mindset on Federal Reserve

Seriously, it is hard to hide my contempt of this disgusting scene. This band of fools somehow believes that prosperity can be created by printing money without any consequences whatsoever. The US is sinking under a mountain of indebtedness and the Fed chairman tells us that it stands ready to engage in even more QE should the need arise. Flash to Ben – the need shall arise. China is already balking at buying US debt meaning you are going to have to buy it all yourself Ben.

What we are witnessing is the death throes of a debt-based monetary system of which those presiding over it apparently have come to believe their own delusions. The US public is learning what our grandfathers learned as a result of the Great Depression – Debt is something to be avoided – not heaped up and accumulated. That the borrower becomes the lender’s slave and that living beyond ones own means is inherently foolish and dangerous. That saddling one’s children and grandchildren with a debt burden that they did not create is immoral and wicked. Yet, all of this is lost upon the monetary lords who have their noses so close to the ground sniffing out the scent that they cannot see the path ahead leads off the edge of an abyss from which there is no escape. Or perhaps they do see and are attempting to secure their own parachutes before leading the rest of the masses over the edge.

I repeat – if lasting prosperity could be created by printing money and giving it away, previous generations that were wiser and more frugal than ours would long ago have stumbled upon this axiom.

That brings us to the war on gold. I am still amazed that after all these years and notwithstanding all the evidence to the contrary, there are still those obtuse enough to insist that there are no official sector attempts to manage or stem the rise in the price of gold. Gold is the only currency that these debasement thieves cannot pollute by conjuring more of it into existence. It rises when distrust of paper currencies is high and confidence in the ability of those who supposedly manage monetary affairs wanes. Thus it is and always will be in direct competition with unbacked fiat currencies.

Our money masters hate the yellow metal because its rise mocks their absurd assertions and debunks their claims of being able to “manage the economy”. It strikes, dagger-like, at the very hubris of these elitists who think that they are wiser than the collective judgment of the entire market, they alone possessing such keen insight into the nature of these matters that we should entrust our financial health to their hands. Imagine the conceit of a few men who think that by pulling on this lever or pushing on this button, that they can assure continuous prosperity and lasting wealth for all. Every generation considers itself wiser than the previous one which is why history does indeed repeat itself. Arrogant men never learn for they lack the one thing essential to make one truly wise – the ability to admit that we do not know all things nor that we mere mortals can always fix what ails us.


-Dan Norcini

Tuesday, August 10, 2010

The Story of Spending

Again I have learned with my studies that its really not a left or right, Republican or Democrat, all politicians love to spend our money...

Saturday, August 7, 2010

Jesse's Café Américain: The Inflation and Deflation Debate Deconstructed

Jesse's Café Américain: The Inflation and Deflation Debate Deconstructed: "'What most people call reason is really rationalization. Given a new set of data, most people will search through it only for those example..."

Monday, August 2, 2010

July 10 Net Worth: $58k Overall 6.59% Growth

Another good month for us with the total net worth jumping up by 6.59%. This is the last month before we join our finances! We didn't have much going this month, we did have to put new breaks on one of our vehicles. We just need to keep this up we are feeling really good about our situation...
Lets break it down:

Cash & Savings: We saw a slight dip in our cash savings because of the purchasing of stock and PMs. Hopefully in the next few months we will see some growth as were have started to really kick up the saving for a downpayment for a home. This money grows from money directly transferred from paycheck into my money market, savings account and checking. This bracket holds the funds for insurance, auto maintenance, Roth IRA, and vacation. This is why it can be a little deceiving, it also holds my monthly budget in it. It has about 13-15k sitting around as savings the rest are funds that are going to be used at some point over the year. The rest is used on a daily bases for covering expenses, rent, food, auto, etc...

Stocks/Brokerage: This month we was slight tick up but that is mostly because purchasing of a gold stock Sprott Physical Gold Trust(PHYS) and Penn West Energy (PWE). I have about another 1k in the account which I am eyeing Exelon Corp (EXC) or more Exxon (XOM). As of right now I am holding back and hopefully save up some cash. The list of stocks I own (GLD)(EGO)(AUY)(AVARF)(RGLD)(ZQK)(XOM)(CVX).

*As you can see I am heavy in commodities in my brokerage account. This is all based on my thought that over the next decade the best investments are going to actually be in hard assets. My Roth/IRA/401k are in pretty common index funds and mutual funds so I figure I can go more risky with brokerage. I believe these will out perform equities in the next decade and if nothing else I feel more comfortable with my portfolio diverse. I am bearish on the US Dollar and US Economy, I believe that trillion dollar deficits are not going bode well for the USA.

Retirement 401k: This bracket is just me adding money to my 401k every month. Slight tick up this month...we will wait and see how the stock market plays out come the fall. Until then not tinkering with this.

Retirement IRA's: Slow growth here this month. I still think the market is going to correct itself. I pulled back half of my Roth into cash, so have about half my retirement in cash right now. I will keep cash on the sidelines and just try and max out my fiancés and my Roth's next year. In this bracket I have all Vanguard Funds (VTSMX, VGSTX, VEIEX)

Debts and Liabilities - Vehicle under 8K!! Credit Cards done...

Credit Cards: Breaks on one of our vehicle and flights out to a wedding on the west coast, they will both be payed off by end of the month. I pay off any Credit Card debt monthly.

Car Loan: I am paying 4% APR on it so I am paying a little, but not a ton. Still looking to pay it off early-will probably be a goal this or next year. We are still saving up for a house so not sure its in our best interest to get rid of our cash sitting to be debt free on my vehicle.

May is now in the bank, I am still extremely bearish on the world economy and the US economy...We are headed for a financial storm and it is very important for all of us to be up to date on current events. It time to be prepared for the worse and pray for the best.

One thing I am excited about next month is the we will be combining our finances in August and will be showing it next month...looking for a jump in total net worth. Until then good luck with your own budget and growing your wealth.

Tuesday, July 20, 2010

Monday, June 14, 2010

How To Save On a Wedding

This is a guest post by Sharon Smith. She offers advice on frugal living and various debt management programs. She can be contacted at findsharonsmith@gmail.com

Church Bells, Wedding Day,
Dating Hell gone away,
What I've Dreamed all my life,
soon to be man and wife.

Are you humming this in your mind? Is it time for you to get betrothed? This is one of the biggest moments in our life. We tie the knot and take vows to be together for a lifetime. Getting pronounced and Man and Wife always call for a beautiful ceremony. Even I had one, so in order to fulfill my desire I got too extravagant and had to part with all my savings. However the lesson here is for a beautiful wedding you need not always put your bank balance at stake. Instead a smart approach towards spending can fetch a better result. Through my own experience I can throw some light on how you can save money on wedding with out giving up on the grandeur of your dream marriage.

Stop spending all your fortune behind wedding. Money can never buy love as the adage goes. So a good planning and some frugal tips can really make your D day worth cherishing.

Here are snippets of some of those frugal wedding mantras that I learnt from my wedding and now letting it out to you.

Wedding guest list needs to be pruned: You can save an enormous amount of cash if you start pruning your guest list. Often there are people who are your acquaintance and not friend. Try to cancel them from the list. Call people who are close to you and your family. Don't take the pressure of inviting all your office colleagues. Invite only the couples instead of inviting their whole family that includes the children.

Save on wedding invitation card as well as on postage: Send an e- card instead of a printed card. It would surely help you save a lot. You can also order a plain invitation and decorate it yourself. Show your creative streak. It's fun! Instead of a reply card ask your near and dear ones to reply on line. This also saves you postage expenses.

Make your wedding dress, make up and hair simple yet elegant: Simplicity is the toughest job. Did you know that? With expensive gowns or an uptown hair-do, you can always look beautiful. But a simple and classic look can actually make your fiancé smitten by love! Try not to hire a designer to design your gown as they won't give you some thing out of the world. If your mother's wedding gown is in perfect condition then you can alter as well as redesign it and use it for your self. It would be nostalgic wearing your mother's wedding gown. This would save a lot of money too. Try to hire someone who is competent in hair do as well as in make up.

Use cash instead of credit cards: Try to use cash while you go out for shopping instead of depending on the credit cards. There is always a tendency to spend more when we use these plastic cards. It becomes really difficult to pay off the piling debts soon after marriage. If you do not use the credit card then you do not have to settle credit card debt. If you get things on cash you can keep a check on the amount you are spending. It would even restrain you from being a spendthrift as well as help you to save money without incurring debts.

Save money on decoration: Decoration means making the wedding place beautiful. That can be a simple gladiola or some nice white drapes! So you can always choose something that will cost you less. You need not go for a rose-laden pathway. Rather just sprinkle some wild flowers and walk away with your spouse. What is important is being together. Before shopping for the decorative item go through an Internet search looking for the cheap stores and bargain prices. Dollar stores have nice and simple products that can be used as an item for decoration like candles, candle holders and plastic flowers. Use silk flower to decorate the reception venue and the church. Silk flowers instead of original flowers can be pocket friendly. The flowers can be too expensive especially during the off season. So some chic artificial flowers can also make your day. Save money by getting silk flowers.

Select a cost-effective menu when it comes to Wedding Food and Drink: Wedding calls for sumptuous brunch or a nice cocktail dinner. But you can always go for a simple yet filling menu. Talk to your caterer stating the motive that you are planning to save money. They would tell you whether a buffet would be less expensive than a seated dinner. The liquor provided by the caterer might cost you more as they would levy extra tax on the total amount. It would be cheaper for you to shop for the liquor in a bulk as they might give you concession. Serve the cocktail after the dinner is laid. And if your fiancé is not too fond of drinking then you may consider organizing a dry wedding.

Don't hire a professional photographer: Even if you hire a professional photographer give him the contract to capture some special moment. If you ask him to take picture of the whole occasion then he might charge you much more. You can afford to pay him for few snaps he would be clicking. Ask your family members and friends to click the wedding photographs. There might be few members in the family as well in the friend circle who can be talented enough to take photographs. In this you can avoid the unnecessary expenses of hiring a professional photographer.

Take my word and do what others might not have done before. A simple wedding can be way above an expensive ceremony. Get closer with your family and friends on this auspicious day! The essence is being together and sharing the best moment of your life! You can have a beautiful wedding and save money at the same time. Just make sure, not to start your newly married life on debts.

Friday, June 11, 2010

Wedding Time

Hey guys, sorry for not posting in a long time. I am headed out for my wedding so I will not be posting here for the next couple of weeks. Check back though, because I will have a guest post on saving money on weddings.

In the mean time, check out some of these previous post:

Thomas Sowell: The Pattern of Failure (this applies so well today)

Wednesday, June 2, 2010

May 10 Net Worth: Chugging along...

Another increase in net worth, only by 2.4% but we will take it! This is the first time in last five months that my total assets have gone negative. It fell only -.23% so not a big hit but still not a gain, mostly from stock market pullback. Either way still positive growth overall.
Lets break it down:

Cash & Savings: This month we managed to grow by $550.00. Not a lot but considering how much we are spending on the wedding, I feel this is still really positive. This is probably going to take a hit this coming month because the wedding and the honeymoon which has out vacation fun in this bracket. This money grows from money directly transferred from paycheck into my money market, savings account and checking. This bracket holds the funds for insurance, auto maintenance, Roth IRA, and vacation. This is why it can be a little deceiving, it also holds my monthly budget in it. It has about 13-15k sitting around as savings the rest are funds that are going to be used at some point over the year. The rest is used on a daily bases for covering expenses, rent, food, auto, etc...

Stocks/Brokerage: Slight move down for the stocks that I own...mostly Exxon and Chevron with the decline of crude oil and the BP oil spill. With gold movement it is making all the mining and etfs I have go up as well. Still watching Silver Wheaton Corp (SLW) and could pull the trigger if stock/silver declines. As of right now I am holding back and hopefully save up some cash. The list of stocks I own (GLD)(SLV)(EGO)(AUY)(AVARF)(RGLD)(ZQK)(XOM)(CVX).

*As you can see I am heavy in commodities in my brokerage account. This is all based on my thought that over the next decade the best investments are going to actually be in hard assets. My Roth/IRA/401k are in pretty common index funds and mutual funds so I figure I can go more risky with brokerage. I believe these will out perform equities in the next decade and if nothing else I feel more comfortable with my portfolio diverse. I am bearish on the US Dollar and US Economy, I believe that trillion dollar deficits are not going bode well for the USA.

Retirement 401k: This braket is just me adding money to my 401k every month. Took a slight loss this month in 401k and feel we will be losing a lot more down the line. Think we might be headed for another downturn in the markets until Zimbabwe Ben starts up the printing press again, which should reflate the market.

Retirement IRA's: Slow growth here this month. I still think the market is going to correct itself. I pulled back half of my Roth into cash, so have about half my retirement in cash right now. I will keep cash on the sidelines and just try and max out my fiancés and my Roth's next year. In this bracket I have all Vanguard Funds (VTSMX, VGSTX, VEIEX)

Debts and Liabilities - Vehicle under 10K!! Credit Cards done...

Credit Cards: This is just a more wedding stuff purchased with credit (Wedding outfit), it will be paid off before I am charged - I pay off any Credit Card debt monthly.

Car Loan: I am paying 4% APR on it so I am paying a little, but not a ton. Still looking to pay it off early-will probably be a goal this or next year. We are still saving up for a house so not sure its in our best interest to get rid of our cash sitting to be debt free on my vehicle.

May is now in the bank, I am still extremely bearish on the world economy and the US economy...We are headed for a financial storm and it is very important for all of us to be up to date on current events. It time to be prepared for the worse and pray for the best. I will be saving as much as I can but with the wedding I am going to be running low on cash flow. (sorry used the same statement as last month but I am still in the exact feelings)